How Canadians Are Managing Finances in 2026: Smart Budgeting, New Income Streams, and the Rise of Digital Entertainment Spending
How Canadians Are Managing Finances in 2026: Smart Budgeting, New Income Streams, and the Rise of Digital Entertainment Spending
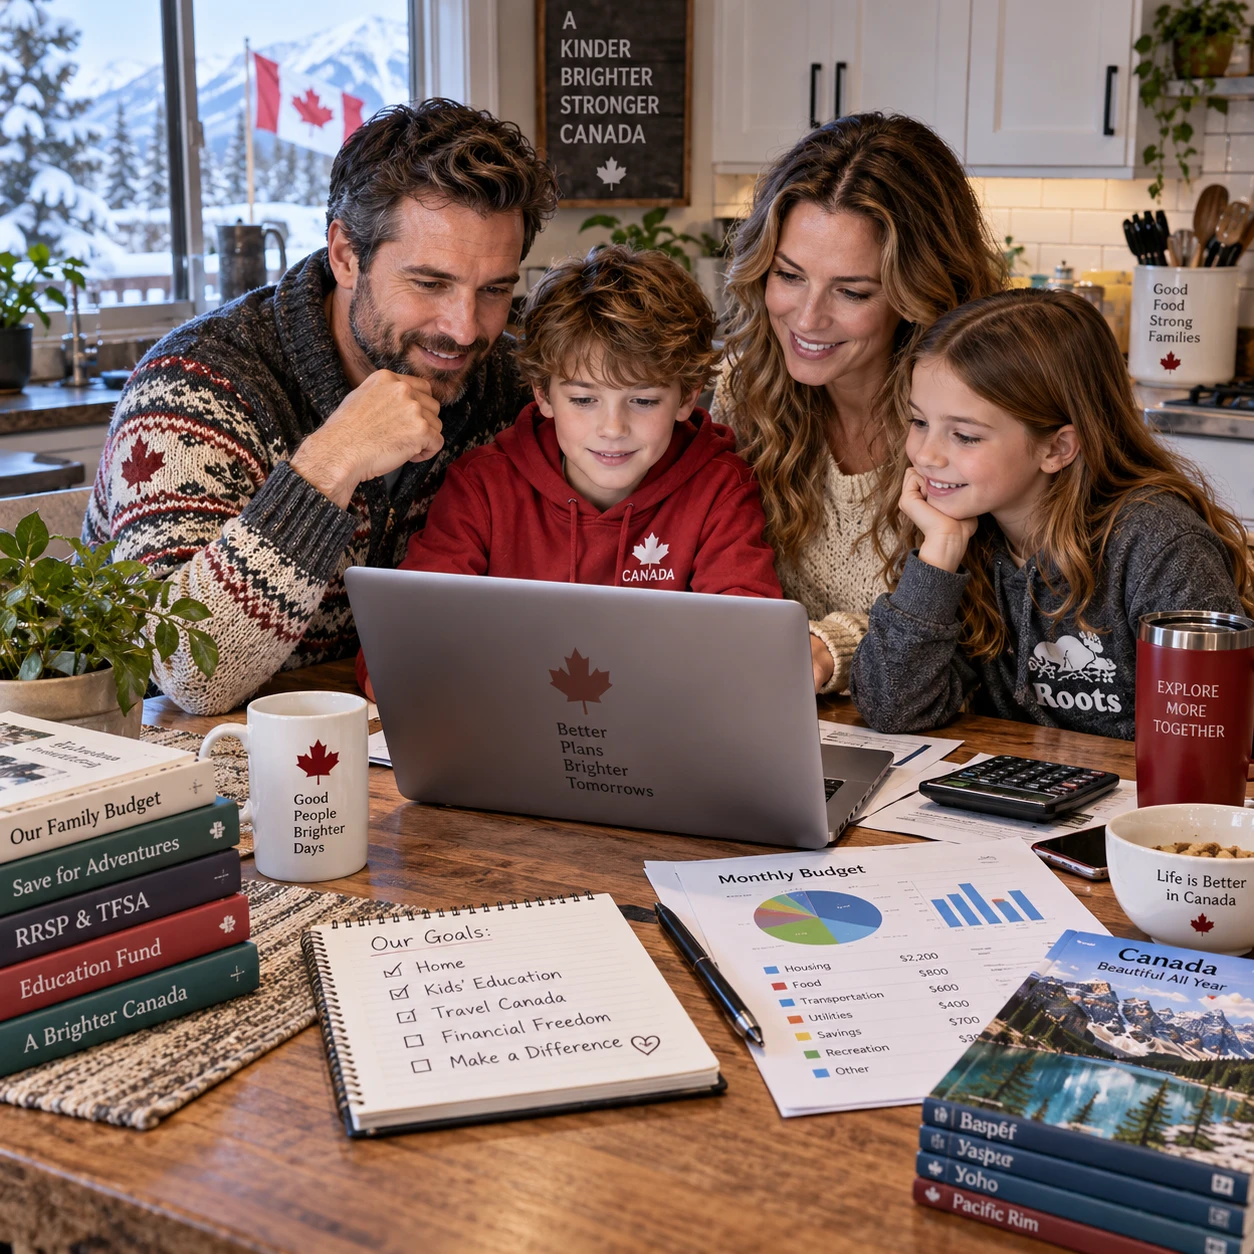
Let's be honest — managing money in Canada right now feels like a juggling act, and not the fun kind. Grocery bills keep creeping up. Rent or mortgage payments eat a bigger slice of the paycheck than they used to. Interest rates still sting, even with some easing. So a lot of us are rethinking how we handle money, period. I've spent the last few months talking to friends, digging through fintech reports, and paying way closer attention to my own spending than I'd like to admit — and a few patterns kept showing up, over and over. Canadians in 2026 aren't just tightening belts. They're getting smarter, a bit more creative, and genuinely more deliberate about where every dollar lands. That covers budgeting, obviously. But it also stretches into side income, investing, and — maybe surprisingly — entertainment spending, including the growing world of crypto-based gaming platforms.
The State of Canadian Household Budgets in 2026
If you've felt like your paycheck doesn't stretch as far as it used to, you're not imagining it. Housing costs across most major Canadian cities remain stubbornly high, and even smaller towns have seen noticeable upticks in rent. Grocery inflation has cooled a bit from its peak years ago, but prices are still elevated compared to pre-2023 levels — ask anyone who's bought ground beef lately. Add in interest rates that, while easing somewhat, still make borrowing pricier than most of us would like, and you end up with a financial environment that demands more attention than it used to.
That pressure has shifted priorities. Where Canadians once budgeted loosely around general categories, there's now a sharper focus on tracking every expense, questioning subscriptions, and asking whether discretionary spending — including entertainment — actually lines up with the bigger goals.
Common Budgeting Challenges Canadians Face Today
The biggest struggles I keep hearing about are debt management, unexpected expenses, and the constant tug-of-war between saving for the future and just covering today's costs. Credit card balances have crept up for a lot of households. Car repairs or medical bills show up at the worst times — they always do. Retirement contributions get pushed aside when short-term needs feel more urgent, which, fair enough, they often are. It's not laziness or bad planning. It's just the reality of juggling multiple financial pressures at once in an economy that doesn't leave much slack.
Smart Budgeting Tips for Canadians in 2026
So what actually works? A handful of strategies have proven their worth, especially in the Canadian context. Zero-based budgeting — where every dollar of income gets assigned a job before the month even starts — has gained real traction, mostly because it forces intentionality. Instead of wondering where your money went, you decide in advance where it's going. Simple idea. Surprisingly effective in practice.
Automating savings is the other big one. Setting up automatic transfers to a Tax-Free Savings Account (TFSA) or Registered Retirement Savings Plan (RRSP) the moment your paycheck lands means you're saving before you even get the chance to spend it. These accounts remain some of the best tools Canadians have for building wealth tax-efficiently, and more people are finally putting them to full use in 2026.
- Prioritize TFSA contributions for flexible, tax-free growth
- Use RRSPs strategically around higher-income years for tax deferral
- Build an emergency fund covering three to six months of expenses
- Review recurring subscriptions quarterly to cut unnecessary costs
Digital Tools and Apps Canadians Are Using
Canadian fintech has matured a lot — these apps aren't just flashy anymore, they're genuinely useful. Tools that link directly to Canadian bank accounts, sort spending automatically, and send real-time alerts have made it a lot easier to stay on top of things without burning hours on spreadsheets. Many now come with built-in goal-tracking, so you can actually watch progress toward a vacation fund, a down payment, or debt payoff. Honestly, that visual piece makes budgeting feel less like punishment and more like progress.
Alternative Income Streams Gaining Popularity
Relying on a single 9-to-5 paycheck feels riskier than it used to, so diversifying income has turned from a nice-to-have into something closer to a necessity. Freelancing and gig work are still popular, sure. But there's also been real growth in rental income — a basement suite, a parking spot, a short-term rental — and in building investment portfolios around dividend-paying stocks and ETFs that generate passive cash flow over time.
The Rise of Side Hustles and Remote Work Opportunities
Content creation, e-commerce, online tutoring — all of it has exploded as supplemental income. I know several people who turned a hobby (photography, baking, teaching a language) into a legitimate side income stream, often entirely online. Remote work flexibility has made it easier to fit these pursuits around a full-time job, and for a lot of Canadians, this extra income is the actual difference between just getting by and building real savings.
Digital Entertainment Spending and the Bitcoin Casino Trend
Here's where things get interesting. As Canadians get more comfortable with digital finance tools in general, that comfort bleeds into how we spend our leisure budgets too. Streaming services, online gaming, digital subscriptions — all long-standing parts of the entertainment mix. But there's a newer trend worth flagging: a growing number of Canadians are putting part of their discretionary entertainment spending toward crypto-based gaming platforms, often called bitcoin casinos.
The appeal makes sense once you look at the mechanics. These platforms run on blockchain technology, which means faster transactions, more transparent odds verification, and a level of privacy traditional online gaming sites don't always offer. For Canadians already holding crypto assets, it's often just a natural extension of how they manage digital money anyway. That said — and this part matters — it needs the same budgeting discipline you'd apply to dining out or streaming subscriptions, no exceptions. If you're exploring this space and want a broader take on fitting a bitcoin casino into a responsible financial plan, it's worth reading up on treating it as one line item among many, not a financial strategy on its own.
Balancing Entertainment Spending with Financial Goals
The golden rule here is simple: set a hard limit before you start, and treat that limit as non-negotiable. Whether it's $50 or $200 a month earmarked for digital entertainment — crypto gaming included — that amount should come strictly from discretionary funds. Never savings. Never debt repayment money. Never emergency reserves. Tracking this spending the same way you'd track a grocery budget keeps things in perspective and stops a casual hobby from quietly turning into a financial problem.
Common Financial Mistakes to Avoid in 2026
A few patterns keep tripping people up, year after year. Lifestyle inflation — where spending creeps up every time income rises — remains one of the sneakiest wealth killers out there. Neglecting an emergency fund is another big one; without that cushion, unexpected expenses often land on high-interest credit cards. Over-leveraging credit in general, whether through loans or buy-now-pay-later schemes, keeps catching Canadians off guard. And impulsive spending — on entertainment, speculative crypto bets, or unchecked gambling — can derail even a well-built budget if it isn't kept in check with clear limits and some basic self-awareness.
Building a Resilient Financial Plan for the Future
The Canadians who seem to be handling 2026 most comfortably aren't necessarily earning more. They're combining disciplined budgeting with diversified income and mindful discretionary spending — that's really the whole trick. That means automating savings, exploring side income where it's realistic, and leaving room for enjoyment, digital entertainment included, without letting it chip away at bigger goals. Financial plans aren't static documents. They need regular check-ins as rates shift, income changes, or life just... happens. A quarterly review of your budget and goals can catch small issues before they turn into big ones.
At the end of the day, financial wellness in 2026 isn't about restriction. It's about balance. Smart budgeting gives you control, alternative income streams give you flexibility, and enjoying modern entertainment options responsibly — bitcoin casinos included — gives you room to actually live your life while still working toward the future you want.